Blog / COI basics
COI basicsWhat does per project aggregate mean on a COI?
A $2 million general aggregate sounds like plenty until you remember it covers every job the contractor works all year. The per project endorsement walls yours off.
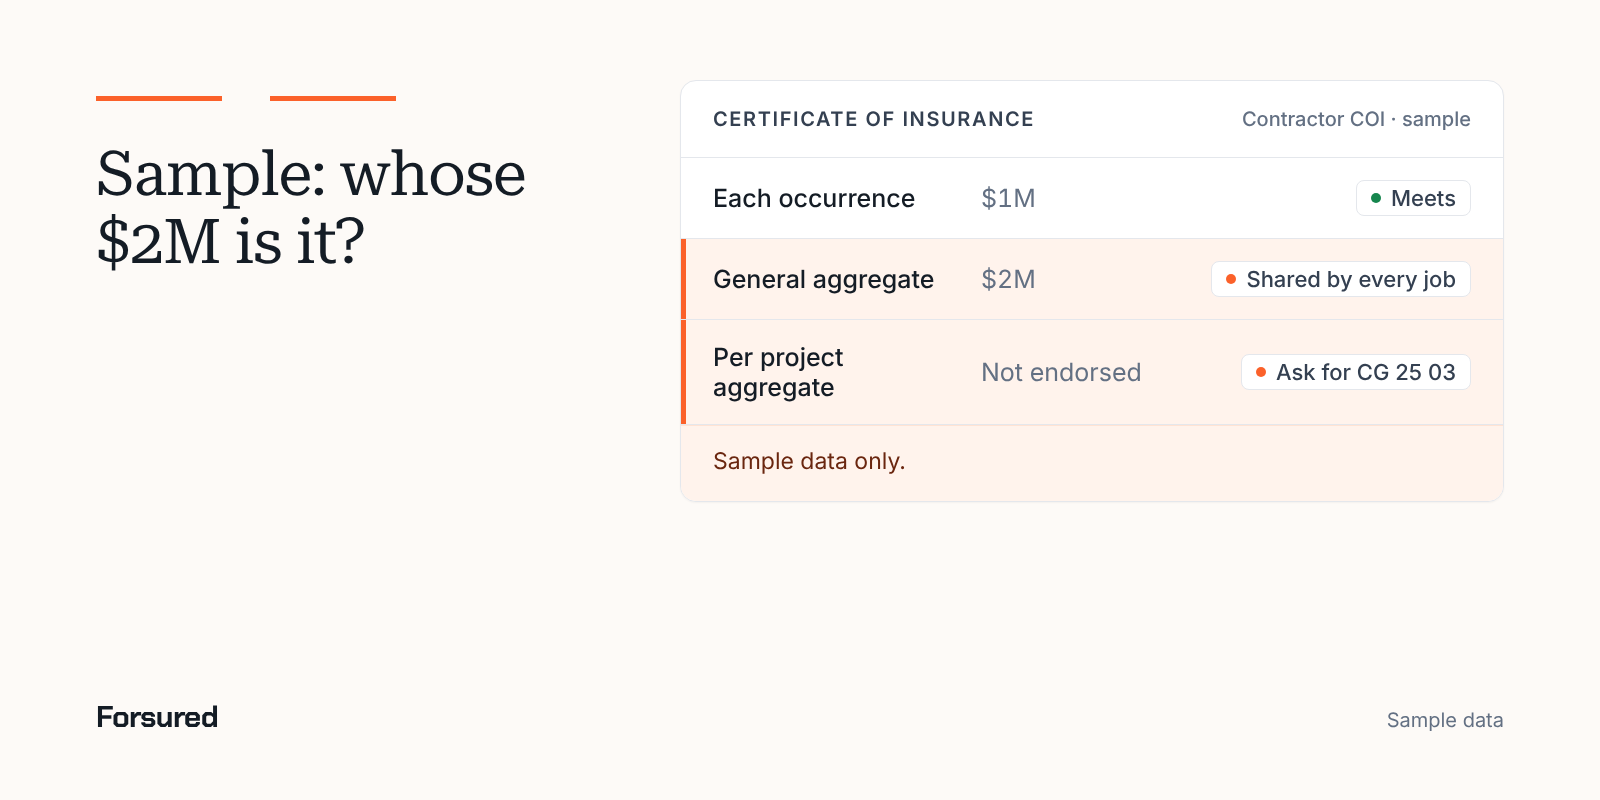
Per project aggregate means the contractor's general liability aggregate applies separately to your project. Without it, one aggregate limit covers every job the contractor works during the policy year, and claims on those other jobs use up the same limit your project is counting on.
What the general aggregate is
A general liability policy has two kinds of limits. The each occurrence limit caps what it pays for any one occurrence. The general aggregate caps the total.
IRMI defines the general aggregate as "the maximum limit of insurance payable during any given annual policy period" for covered losses other than specified exposures. Products-completed operations claims are "paid out of a separate aggregate." Once paid losses reach the general aggregate, "that limit is exhausted and no more losses in any of those categories will be paid."
That's the catch for an owner or GC. A certificate showing a $2 million general aggregate tells you what the contractor bought, not how much of it is left. A busy contractor with a bad year on two other jobs can show up to yours with far less.
What CG 25 03 changes
The ISO endorsement CG 25 03, Designated Construction Project(s) General Aggregate Limit, fixes that. IRMI says it makes "the general aggregate limit apply separately to each designated construction project," which "enables a contractor to comply with contractual requirements" for a specified amount of insurance on a specific project.
The form itself spells out how it works:
- Each project gets its own limit. "A separate Designated Construction Project General Aggregate Limit applies to each designated construction project."
- Claims stay in their lane. Payments for a claim tied to one project reduce that project's limit and "shall not reduce any other Designated Construction Project General Aggregate Limit."
- Completed operations stay shared. Products-completed operations claims reduce only the products-completed operations aggregate. IRMI confirms the endorsement "does not affect the policy's other limits, including the products-completed operations aggregate limit."
A related form, CG 25 04, does the same for designated locations a contractor owns or rents, as Insureon explains.
What to check on a contractor COI
- Confirm your project requirements call for a per project aggregate, and at what amount.
- Look for it on the certificate, then ask for the CG 25 03 endorsement or the insurer's equivalent.
- Check the schedule. It should name your project, or say it applies to all construction projects.
- Remember completed operations. CG 25 03 doesn't separate that aggregate, so check its amount on its own.
Forsured checks each contractor COI against your project requirements, including the endorsements behind the limits shown, for the life of the job.
Get new posts by email.
New posts on contractor COIs and project requirements, plus the coverage gaps we're seeing on real projects. Short and plain.
You're on the list. Thanks for reading.
No spam. Unsubscribe from any email.
About Forsured
Forsured is construction insurance compliance software for general contractors and the brokers who insure their trade contractors. You set each project's insurance requirements once. Forsured reads every contractor COI and endorsement against them, flags each gap with the reason, and keeps checking through renewals until the job is done.
- Project requirements with exceptions, not one template for every job
- Endorsement review (additional insured, waiver of subrogation, primary and noncontributory), not just the certificate
- A shared workspace where the contractor's broker sees exactly what's missing
- A person on your team approves every result, with a full review history
“What stood out to us is that Forsured doesn't just organize the paperwork. It helps us understand what meets the project requirements, what needs attention, and what needs to happen next. That clarity across the GC, subcontractor, and broker is where we see the real value.”
Send us one project's requirements and a contractor COI or two. We'll show you every gap we find, free.
Common questions
What is a general aggregate limit?
IRMI defines it as the maximum the policy pays during the policy period for all covered losses other than specified exposures. Products-completed operations claims come out of a separate aggregate. Once paid losses reach the general aggregate, it's exhausted.
Does CG 25 03 cover completed operations?
No. IRMI notes the endorsement doesn't affect the policy's other limits, including the products-completed operations aggregate. Under the form, products-completed claims reduce only that aggregate, which stays shared across all the contractor's finished work.
Is a per project aggregate required by law?
No. It's a contract term. Owners, GCs, lenders and bonding companies often require it in project requirements, and the contractor's insurer adds it by endorsement.
Sources
- General aggregate limit (definition), IRMI
- Designated construction project general aggregate limit endorsement (definition), IRMI
- CG 25 03 05 09, Designated Construction Project(s) General Aggregate Limit (ISO form, hosted by NY OGS), New York State Office of General Services
- Per Project Aggregate Endorsement for General Liability, Insureon, Jul 20, 2026
We link to the original reporting and research behind every post. This post is general information, not legal or insurance advice: Forsured is a software company, not a law firm or a licensed insurance agency, so confirm anything you'll rely on with your broker or attorney. Spotted something we got wrong? Write to hello@forsured.ai and we'll fix it.